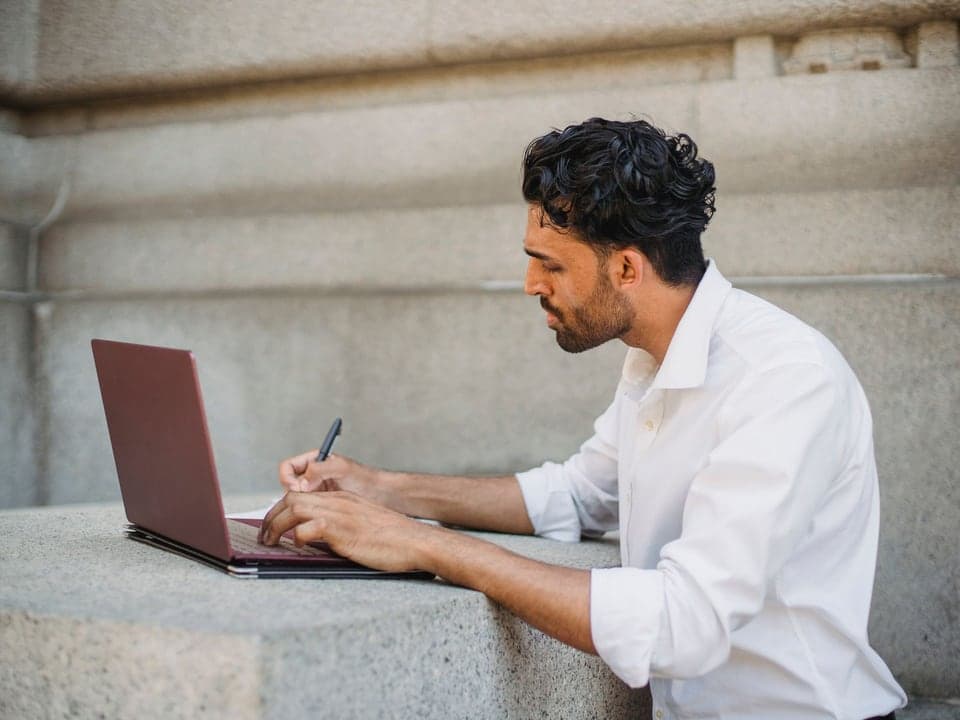
Self-employed & freelancers
No employer plan, no group rate, and 1099 income that moves month to month.
Licensed advisors in all 50 states
Real plans from nationally recognized carriers, reviewed with you by one licensed advisor who actually picks up the phone. No pressure, ever.
USA Health Savings
Let’s find your coverage
Secure & private. By submitting you agree to be contacted by one licensed advisor.
Plans from nationally recognized carriers
The Honest Comparison
Unsubsidized bronze-tier premium, $5,000+ deductible.
vs
Pre-existing conditions covered
 $300/mo
Underwritten PPO coverage for a healthy applicant.
Save ~$450/mo — that's over $5,400 a year back in your pocket.
Actual premiums, deductibles and benefits vary by age, location, health history and the plan selected.
| Feature | Marketplace | Best Value |
|---|---|---|
| Monthly premium | $750/mo | $300/mo |
| Deductible | $5,000–$9,000+ | As low as $0 |
| Telemedicine | ~$50 a visit | Often $0 |
| Doctor & specialist visits | $50+ copays | Low or $0 copays |
| Out-of-pocket max | $18,000+ | ~$3,000 |
| Co-insurance | Often 40% on you | Up to 100% covered |
| Doctor networks | Narrow local HMOs | Broad nationwide PPOs |
| Enrollment window | 6 weeks a year | Any day of the year |
Best ValueMonthly premium
Deductible
Telemedicine
Doctor & specialist visits
Out-of-pocket max
Co-insurance
Doctor networks
Enrollment window
What actually moves the price
Tap an option to see how it moves a typical monthly premium.
Typical monthly range
$220 – $295
General example, not a rate or offer. If a subsidy makes the Marketplace cheaper, an advisor will tell you.
Start My Free ReviewIndustries we serve
No employer plan, no group rate, and 1099 income that moves month to month.
Covering yourself first, then deciding what you can offer a small team.
Physical work, seasonal income, and a real need for specialist access.
Commission income that subsidy math handles badly.
Care needed in states you don't live in — where narrow networks fail.
The gap between an employer plan ending and Medicare starting.
Part-time hours that never quite reach benefits eligibility.
Income that swings enough to make a fixed premium the safer bet.
How it works
Coverage by state
Hover or tap your state
Licensed advisors serve all 50 states. Plan availability and underwriting rules vary by state.
Member stories
The advisor told me my wife's subsidy made the Marketplace cheaper for her, and put me on a private plan by myself. Two plans, less money.
I lost coverage in March. Open enrollment was eight months away. That was the whole problem, and it took one call to solve.
I asked about a condition I assumed would disqualify me. It didn't. What I needed was someone to actually read the exclusions with me.
He walked me through what the plan does not cover before he told me what it does. That is the part I did not expect.
I drive through six states in a week. A local HMO was never going to work and nobody had said that out loud before.
One call, one follow-up email, then nothing until I answered. After the year I'd had with lead sites, that was the selling point.
We were nine months out from Medicare and the COBRA number was absurd. The gap plan cost less than half.
My income is different every month. She built the comparison around that instead of asking me to guess a number.
I expected a sales pitch. I got a spreadsheet and a straight answer about the deductible.
They told me my daughter qualified for CHIP and that we should take it. It cost them the bigger sale.
The specialist I already see is out of state. That was the first question he asked, before anything about price.
Applying in June instead of waiting until January was the entire answer. I just did not know that was possible.
One call, then it's your move
USA Health Savings
Let’s find your coverage
Secure & private. By submitting you agree to be contacted by one licensed advisor.
Five questions, one licensed advisor, zero pressure. If private coverage isn't your best option, we'll tell you that instead.